The headlines drop with predictable monotony. Another think tank releases another glossy index, declaring Hong Kong the world's freest economy while Switzerland edges out Singapore. Technocrats nod. Business journalists dust off tired templates about regulatory efficiency, tax rates, and ease of doing business.
It is all a comforting illusion. Recently making headlines lately: The Architecture of Exit Control Sovereign Friction and Capital Retention in Modern Geoeconomics.
For decades, economists have treated freedom like a spreadsheet exercise. They count the days it takes to register a company, tally up the corporate tax brackets, and measure trade tariffs. They produce neat, color-coded maps that tell investors where to park capital based on administrative convenience.
I have watched multinational corporations spend millions chasing these glowing rankings, only to find themselves trapped in rigid systemic constraints the moment a crisis hits or geopolitical gravity shifts. They buy into a metric that mistakes bureaucratic grease for actual liberty. Additional information on this are explored by The Wall Street Journal.
Real economic freedom has nothing to do with how fast you can file corporate paperwork in Central or Zurich. It is about the absolute autonomy of capital, the complete absence of political coercion in asset allocation, and the sovereign right of an individual to transact without state surveillance or conditional permission.
By treating economic freedom as a collection of administrative checklists, these indexes blind us to structural capture. Let us tear down the lazy consensus and look at what is actually happening beneath the polished veneer of the global economic freedom rankings.
The Statistical Sleight of Hand
Let us start with the methodology. Heritage Foundation, Fraser Institute, and the World Bank love to score jurisdictions on a curve of procedural friction. If you can open a shop in three days, you get a gold star. If the tariff code is thin, you rank near the top.
This approach suffers from a fatal flaw. It measures the ease of compliance, not the depth of independence.
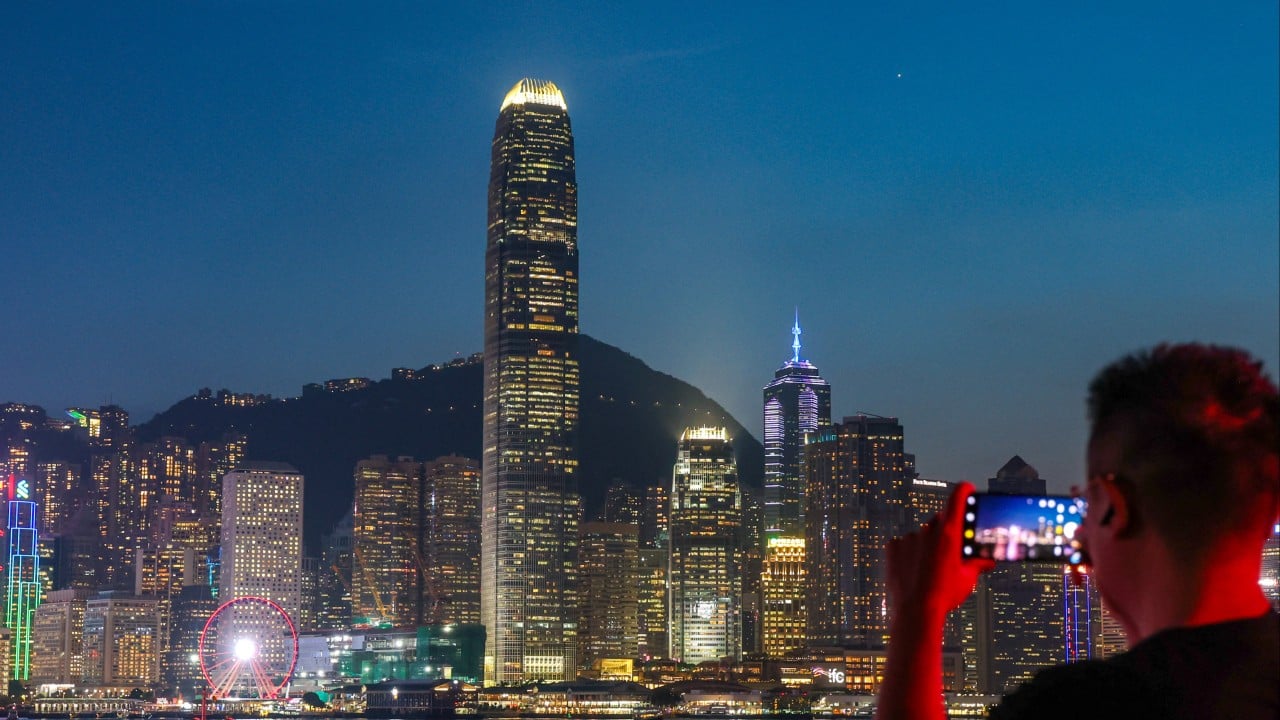
Take Hong Kong. For years, index compilers have kept it pinned to the top of the leaderboard because its nominal tax rates remain low and capital flows are legally unrestricted. But look closer at what has actually transpired on the ground. When regulatory alignment shifts overnight to reflect the political imperatives of an authoritarian mainland, the legal foundations supporting that freedom morph. Capital might still move, but the rule of law—the invisible architecture that gives capital its actual value—has been fundamentally re-engineered.
A system where property rights are contingent on geopolitical loyalty is not a free economy. It is a golden cage with a low tariff wall.
Switzerland pulls off a similar trick from a different angle. It ranks brilliantly because of a deeply entrenched banking establishment, conservative fiscal policies, and decentralized cantonal governance. Yet, Swiss
Why the Free Economy Rankings Are a Complete Joke
business, news
Every time the annual economic freedom indexes drop, the financial press loses its mind. The consensus headlines read like a corporate brochure for tax accountants: Hong Kong holds the crown, Switzerland surges past Singapore, or vice-versa depending on which think tank is funding the clipboard brigade this quarter. Business leaders nod gravely, sovereign wealth funds rebalance their spreadsheets, and mid-level bureaucrats in Geneva or Wan Chai pop cheap prosecco.
It is all smoke and mirrors.
I have watched multinational conglomerates spend millions restructuring regional hubs because a single line item shifted three decimal places on a Heritage Foundation or Fraser Institute scorecard. They treat these rankings like gospel. They are not gospel. They are a bureaucratic fiction built on legacy metrics that measure how easy it is to file paperwork, not how capitalism actually operates in the dirt and noise of the real world.
Stop looking at index scores. They are lying to you.
The Bureaucratic Blind Spot
Let us define what these indexes actually measure. They look at tariff rates, property rights enforcement speed, business registration friction, and monetary policy stability. On paper, this makes sense. A country with low taxes and fast permit approvals looks like an absolute paradise for capital.
Except this methodology suffers from a fatal flaw. It measures the ease of incorporation, not the survival rate of enterprise.
Imagine a scenario where a territory lets you register a corporate entity in four minutes flat with zero capital requirements. The indexers hand them a gold medal for economic freedom. But what happens on day 365 when your local banking partner freezes your corporate account because your supplier is based in a sanctioned zip code, or when invisible administrative pressure quietly tells your landlord that renewing your lease is a bad idea for national stability? The index registers the effortless entry. It completely misses the inescapable exit.
Real economic freedom is not about how fast you can start a business. It is about whether you can keep your capital, speak your mind, pivot your supply chain, and protect your enterprise from arbitrary state intervention when the political winds shift. By that standard, the current leaderboard is upside down.
Switzerland overtakes Singapore? Singapore surges ahead of Hong Kong? It is a shell game. You are arguing over whether a gilded cage has velvet lining or leather upholstery while ignoring the padlock on the door.
Dismantling the Singapore and Hong Kong Myth
Let us talk about Singapore. The consensus view is that Singapore represents the pinnacle of frictionless commercial liberty. I have spent enough time in the financial district there to know the reality is far more nuanced.
Singapore is a masterpiece of state-directed capitalism. It is efficient, pristine, and ruthlessly organized. But freedom? True economic freedom requires the chaotic oxygen of trial, error, and institutional friction against overreach. In Singapore, the government is your landlord, your housing developer, your workforce planner via central labor controls, and your largest shareholder through Temasek and GIC.
When the state owns the land, dictates demographic inputs, and influences commercial credit allocation with surgical precision, calling it a bastion of unbridled free-market capitalism is an insult to Adam Smith. It is a highly optimized corporate meritocracy governed by a very smart, very interventionist committee. That works brilliantly until your strategic goals diverge from the state's five-year plan. Try launching an industry that competes directly with a government-linked corporation and see how frictionless your market entry feels.
Now look at Hong Kong. The mainstream narrative treats Hong Kong's economic freedom as either entirely dead or entirely intact depending on the political bias of the publication. Both extremes are lazy.
Hong Kong remains a powerhouse of raw commercial velocity. The capital flows are deep, the tax code is brutally simple, and the proximity to mainland manufacturing muscle is unmatched. But pretending that traditional rule of law and common-law contractual security operate identically to how they did twenty years ago is corporate gaslighting. When local courts face structural overrides, and compliance departments in Western banks spend half their day vetting transactions for geopolitical landmines, the "freedom" to do business comes with an invisible risk premium that no spreadsheet captures.
Yet the indexers keep awarding top marks because the statutory corporate tax rate is low and filing a VAT return does not require a blood sacrifice.
The Swiss Exception That Proves the Rule
Switzerland is the darling of the current cycle, vaulting upward in various competitiveness metrics because of its stability, institutional continuity, and decentralized cantonal tax competition.
Here is the truth nobody in Geneva wants to say out loud: Swiss economic freedom is an exclusive club for incumbents.
Try launching an ambitious, disruptive retail bank or a high-risk fintech challenger in Zurich without twenty generations of local connections and a compliance budget the size of a small nation's GDP. The regulatory moat is designed to protect existing wealth, not foster dynamic market entry. It is stable, yes. It is predictable, yes. But freedom implies the right to fail quickly, experiment wildly, and disrupt incumbents without needing a stamp of approval from a cantonal trade guild.
Switzerland is the ultimate wealth preservation machine. It is not an engine of aggressive, permissionless economic creation. Conflating the two is why venture capital ecosystems in Zurich look like retirement homes compared to the messy, high-failure-rate chaos of early-stage hubs elsewhere.
What You Should Be Measuring Instead
If you are deploying capital, building an international supply chain, or choosing where to plant your corporate flag, throw away the macro-index league tables. They measure the past. They measure what is easy to quantify rather than what actually matters.
Instead, audit your exposure using three brutal questions:
- The Exit Velocity Test: If you need to pack up your IP, your treasury, and your key personnel and leave within thirty days, can you do it without the state seizing your assets or throwing administrative roadblocks in your path?
- The Incumbent Immunity Check: Does the local regulatory framework actively protect entrenched monopolies and state-backed giants, or does it genuinely tolerate disruptive startups that threaten the status quo?
- The Arbitrary Intervention Threshold: Is the rule of law predictable based on written statutes, or does it bend based on unwritten political imperatives and backroom phone calls?
The answers to these questions will tell you more about the true state of an economy than a thousand pages of data compiled by think tanks sitting in Washington, Geneva, or London.
The next time you read a headline declaring a new champion of economic freedom, look past the ranking. Look at who is holding the stopwatch, and ask yourself what they are failing to time.
Stop chasing the indexes. Build resilience instead.