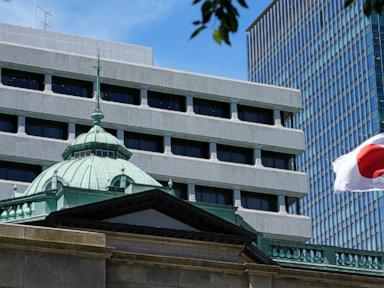
For decades, borrowing money in Japan felt almost free. While the rest of the world battled inflation spikes and soaring mortgage rates, the Bank of Japan clung stubbornly to negative interest rates, propping up an economy stuck in perpetual slow motion. That era is officially dead.
When the central bank pushed its benchmark policy rate to 1.25 percent following consecutive hikes earlier in the year, it marked the highest borrowing cost the country has seen since the mid-1990s. This isn't just a routine monetary adjustment. It signals a complete structural U-turn for an economy that spent a generation fighting deflation. If you think this only matters to Tokyo bond traders, you're missing the bigger picture.
The End of Cheap Money and Why It Took Thirty Years
Japan spent thirty years trapped in a economic holding pattern. Whenever growth stuttered, the central bank flooded the system with liquidity, driving interest rates down to zero and eventually below it. Consumers got used to stagnant wages, companies sat on massive cash piles instead of investing, and the yen became the ultimate funding currency for global carry trades.
Governor Kazuo Ueda didn't abandon this playbook overnight. But sustained underlying inflation hitting the bank's elusive 2 percent target forced their hand. Workers finally secured meaningful wage increases during annual labor negotiations, creating the wage-price feedback loop policymakers had prayed for since the nineties.
When rates moved from 1 percent up to 1.25 percent, the central bank crossed a psychological Rubicon. They stopped treating ultra-loose monetary policy as a permanent safety net and started treating it as an emergency measure that had outlived its purpose.
Winners and Losers in a Normalizing Market
You can't normalize interest rates after thirty years without creating massive portfolio shifts. The fallout is already rewriting balance sheets across sectors.
Japan's major banking groups are posting record profits. Lenders who spent decades struggling to make a margin on zero-percent loans suddenly find themselves swimming in net interest income. Combined net profits for the country's top banking heavyweights are tracking toward historic highs above 7 trillion yen, proving that traditional banking models work a lot better when money actually costs something.
Real estate tells a more nuanced story. Higher borrowing costs usually cool property booms, but prime commercial and residential sectors in Tokyo continue attracting heavy institutional capital, driven by strong rental growth. Investors aren't fleeing; they are just getting picky. Cheap leverage is gone, meaning projects have to generate real cash flow rather than relying on subsidized financing.
Consumers face a steeper adjustment. Mortgages are creeping up from rock-bottom floors. Savers are finally seeing positive yields on bank deposits, though decades of deflationary habits mean many households are still hesitant to deploy cash into risk assets.
The Currency Puzzle and Global Shockwaves
The weak yen created a domestic headache that forced the central bank's hand. Even at 1.25 percent, Japanese rates sit well below those in the United States and Europe. That narrow differential kept downward pressure on the currency, inflating import bills for a country that relies heavily on foreign energy and food.
When the currency slid past historic thresholds earlier in the year, policymakers realized that defending the yen required more than occasional market intervention. It required actual monetary tightening.
Global investors who borrowed cheap yen to buy higher-yielding assets abroad—the infamous carry trade—are feeling the squeeze. Every time Tokyo hints at another rate hike, ripples hit global equity and bond markets.
What Comes Next for Monetary Policy
The debate inside the central bank has shifted from whether to normalize rates to how fast the normalization should go. Economists and former policymakers are already projecting rates to edge closer to 1.5 percent or higher, with some models pointing toward 2 percent as the eventual neutral destination.
Board members remain divided. Some argue that persistent labor shortages and entrenched inflation demand faster tightening to keep price pressures under control. Others urge caution, warning that fragile consumer demand could buckle if borrowing costs rise too quickly.
Watch the upcoming quarterly data releases closely, particularly household spending metrics and wage-growth continuation. If corporations keep passing higher labor costs onto consumers without destroying demand, the central bank will have all the justification it needs to keep climbing. The era of free money in Tokyo is officially over, and the financial world is still learning how to operate in gravity.