Read that headline again. "Chinese battery giant CATL hit by profit slowdown as EV headwind fears grow." Lazy. Predictable. Completely backward.
When a cell maker with gigawatt-hour scale posts slower profit growth during a price war and a cooling EV curve, lazy analysts reach for the nearest cliché: the EV boom is stalling, and CATL is getting squeezed.
Wrong question. Wrong diagnosis. Wrong timeline.
A slowdown in top-line profit growth for Contemporary Amperex Technology Co., Limited—better known as CATL—is not a funeral bell for electrification. It is what happens when an industrial dominant player stops acting like a hyper-growth startup and starts operating like a chemical-and-grid utility during a raw-material deflation cycle. Confusing pass-through pricing and temporary margin compression with structural demand collapse is how retail investors get shaken out right before the next industrial leg up.
I have spent years sitting across from supply-chain executives, cell engineers, and industrial procurement teams. I have seen companies blow millions on this exact mistake—treating a single quarter's margin wiggle in a commodity-linked hardware business as proof that an entire multi-decade energy transition is over. If you judge a cell manufacturer by headline net-income growth rates without separating lithium carbonate pass-throughs, factory utilization, and stationary storage demand, you are flying blind.
The Lazy Consensus Around EV Headwinds
The standard narrative goes like this: electric vehicle sales growth moderates in key markets, automakers push back launch schedules or trim sticker prices, cell prices fall, and CATL's profit growth decelerates. Therefore, EV demand is cracking.
That logic skips three basic mechanics of how battery economics work.
First, a battery pack is a chemical assembly priced on pass-through formulas. Lithium carbonate and lithium hydroxide prices swung wildly over the past few years—spiking to extreme highs and then sliding hard as new supply came online from Australia, South America, and domestic lepidolite and brine projects. When raw material costs drop sharply, cell prices adjust downward under index-linked contracts. A lower selling price per kilowatt-hour shrinks nominal revenue and narrows percentage optics even when gigawatt-hour shipments keep climbing. Measuring health by raw percentage profit jumps during input deflation is like judging a flour mill by revenue per sack while wheat prices are plunging.
Second, unit profit vs. percentage margin is not the same thing. Suppose a battery maker earns a fixed dollar margin per kilowatt-hour on an entry-level lithium iron phosphate (LFP) pack, and the price of that pack drops because lithium got cheaper. Even if the dollar profit per pack holds steady or shifts slightly, the percentage margin moves. Analysts who stare at percentage growth deceleration often miss that scale, throughput, and working-capital discipline are doing quiet heavy lifting behind the scenes.
Third, EV growth slowing from hyper-growth rates is not a demand cliff. Going from 80% year-on-year growth to 25% or 30% growth in a massive base is arithmetic, not collapse. Every maturing industrial sector hits the law of large numbers. Pretending that slower percentage growth equals EV rejection mistakes a growth-rate normalization for a structural reversal.
You Are Asking the Wrong Question
Most coverage asks: Is an EV slowdown hurting CATL?
That question assumes CATL's fate is tethered exclusively to passenger EVs fighting over cheap compact-car margins. It isn't. The sharper question is: How is CATL converting manufacturing scale, chemistry breadth, and stationary energy storage into long-term industrial moat while weaker rivals bleed cash?
Consider the chemistry split that generalist commentators routinely flatten. Lithium iron phosphate (LFP) and lithium manganese iron phosphate (LMFP) have eaten huge share in standard-range EVs and grid storage because they avoid expensive nickel and cobalt, offer strong thermal stability, and deliver long cycle life at lower cost. Meanwhile, high-nickel ternary chemistries like nickel manganese cobalt (NMC) still serve long-range, performance, and cold-climate niches, and sodium-ion cells target cost-sensitive entry mobility and storage. When a company spans all of those chemistries—alongside fast-charging architectures and battery-swapping ecosystems—a hiccup in one vehicle segment does not equal a dead business.
Look at stationary battery energy storage systems (BESS). Grid operators, utilities, and data-center power buyers need gigawatt-hour and multi-gigawatt-hour blocks to balance solar and wind intermittency, shave peak demand, and stabilize frequency. Stationary storage has different procurement cycles and margin dynamics than auto OEM contracts. Yet headlines still lump everything under "EV headwinds" because "EV" gets clicks.
Imagine a scenario where a European or North American automaker delays a new electric crossover by nine months. Headlines scream about EV headwinds. Meanwhile, a utility scales up a grid storage tender or a commercial fleet orders LFP packs at lower cell costs that finally make total cost of ownership beat diesel on pure payback math. Lower cell prices are a headwind to high-margin pricing power in the short run, yes—but cheaper batteries are also the exact fuel that unlocks mass-market affordability and grid adoption. You cannot simultaneously complain that EVs are too expensive for mass buyers and panic when battery prices fall.
Brutal Answers to "People Also Ask"
Does a profit slowdown mean CATL is losing its dominance?
No. Dominance in cell manufacturing is not won by a single quarter's net income delta; it is won by yield rates, equipment utilization, supply-chain integration, and balance-sheet staying power.
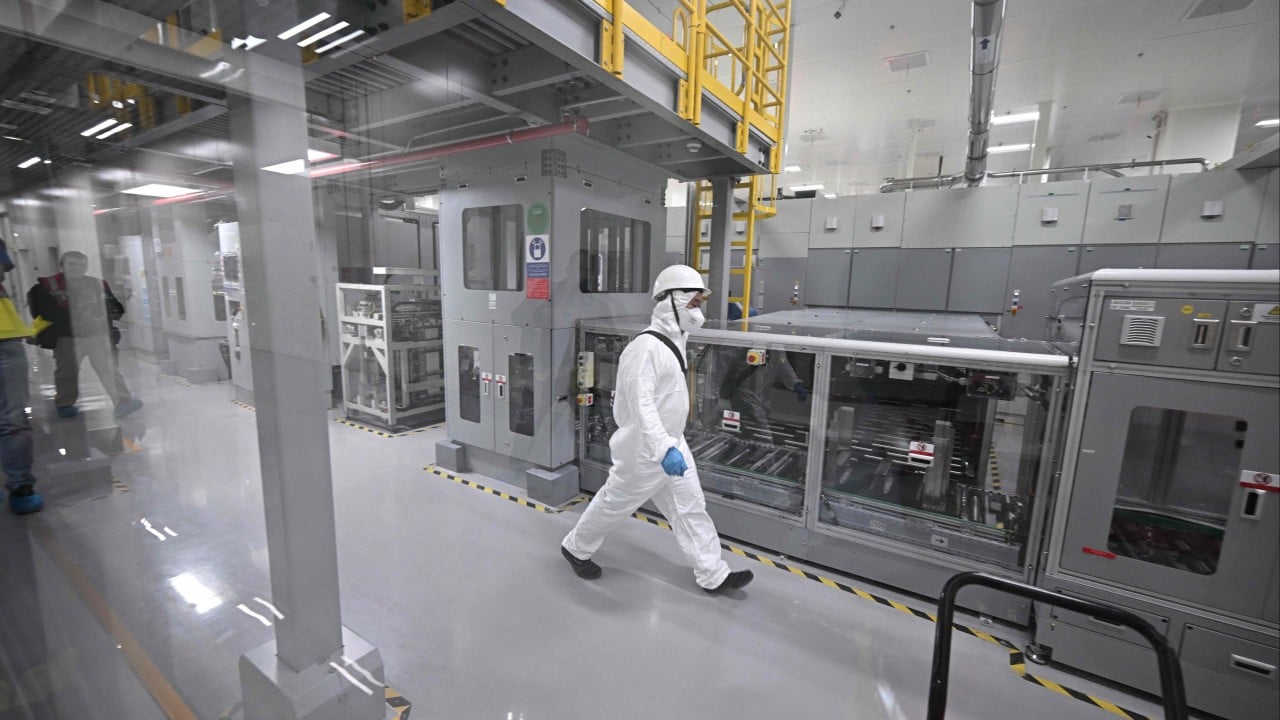
In cell fabrication, scrap rate and yield at scale separate profitable giants from money pits. I have watched ambitious battery startups and legacy joint ventures burn hundreds of millions trying to hit high yields on high-speed electrode coating, calendering, slitting, winding or stacking, electrolyte filling, and formation cycling. Tiny defects cause field failures or thermal headaches; scrap eats margins alive. When pricing gets tough, high-cost, low-yield competitors get crushed first. Tough pricing environments often widen the gap between the scale leader and everyone else—even when the leader's own growth rate slows down.
Are EV headwinds just a polite way of saying people don't want electric cars?
Brutally honest answer: in several markets, buyers don't want badly priced, inconvenient, or poorly suited electric cars—and they definitely don't want to pay a steep upfront premium just to feel virtuous.
Where charging infrastructure is sparse, home charging is impractical, or upfront prices sit out of reach for median households, adoption hits friction. Where prices drop, charging speeds improve, and total ownership math works without subsidies, demand behaves very differently. Blaming "EV headwinds" as a monolithic cultural rejection ignores how sensitive car buyers are to price, range-to-cost ratio, and local infrastructure.
Why wouldn't automakers just make all their own batteries to bypass CATL?
Because building batteries at gigawatt-hour scale is a capital-intensive chemical manufacturing business, not a software tweak.
Automakers are experts at vehicle design, stamping, powertrain integration, brand marketing, and global distribution. Running giant cell plants requires deep chemical engineering, cathode and anode supply coordination, massive upfront capex, and relentless focus on manufacturing uptime. Many automakers still buy cells externally or run joint ventures while keeping core vehicle engineering in-house. Trying to insource everything at once has burned plenty of balance sheets when volume forecasts miss.
The Heavy Hitters and the Real Battleground
To understand where this industry actually stands, look at the voices and institutions that track physical energy systems rather than daily stock chatter. Analysts at BloombergNEF and International Energy Agency (IEA) reports have consistently highlighted how falling pack prices, chemistry shifts toward LFP, and rapid grid-storage deployment reshape global battery demand—even when regional EV sales growth cools or policy shifts create noise.
The real battleground is no longer whether electrification exists. It is:
- Margin discipline during deflation: Holding unit economics and cash conversion together when average selling prices drop.
- Geopolitics and localization: Navigating tariffs, trade rules, local-content mandates, and overseas plant execution without blowing capex budgets.
- Stationary storage and non-auto demand: Turning grid storage, commercial vehicles, and industrial applications into durable profit pillars alongside passenger cars.
- Next-gen chemistries without hype: Moving commercial realities forward—whether better LFP/LMFP energy density, practical sodium-ion deployment, or real-world solid-state timelines—without confusing lab demos with mass-market readiness.
Where My Contrarian Take Can Bite You
Honesty requires putting the downsides on the table. If you take the view that CATL's profit slowdown is mostly cyclical noise rather than fatal rot, here is how that bet can hurt you:
- Price wars can last longer than comfort zones allow: Fierce competition among cell makers can compress margins more deeply and for longer than expected if overcapacity lingers in specific lines.
- Policy and tariff friction is real: Trade barriers, rules of origin, and shifting subsidy regimes can restrict market access or force higher-cost localization that pressures returns.
- Tech disruption is never zero: Even entrenched leaders face risk if rival chemistries or manufacturing breakthroughs leapfrog current architectures faster than modeled.
- Cyclicality still stings: Even when a long-term trend is intact, buying into a cyclical downswing too early or with poor risk sizing still hurts in the short run.
Actionable Moves Instead of Panic
If you are an investor, operator, or procurement lead reading headlines about CATL and EV headwinds, stop reacting to the ticker and do this instead:
- Separate volume, price, and margin: Track gigawatt-hour shipments, average pack pricing trends, and gross/operating margin drivers separately instead of treating net profit growth as a single truth serum.
- Watch storage and commercial fleets: Monitor stationary storage deployments and commercial electrification alongside passenger EV registrations to see where real demand is accelerating.
- Stress-test your assumptions at lower cell prices: If you build hardware, finance projects, or run an energy business, model what happens when pack costs stay lower for longer—it changes both competitive threats and cost-reduction opportunities.
- Audit supply-chain concentration: Whether you are an automaker or an energy buyer, pair cost efficiency with geographic and supplier resilience so a single regulatory or logistics shock doesn't stall your line.
Stop letting lazy headlines do your thinking for you. Look at the chemistry, look at the gigawatt-hours, and price the reality—not the panic.