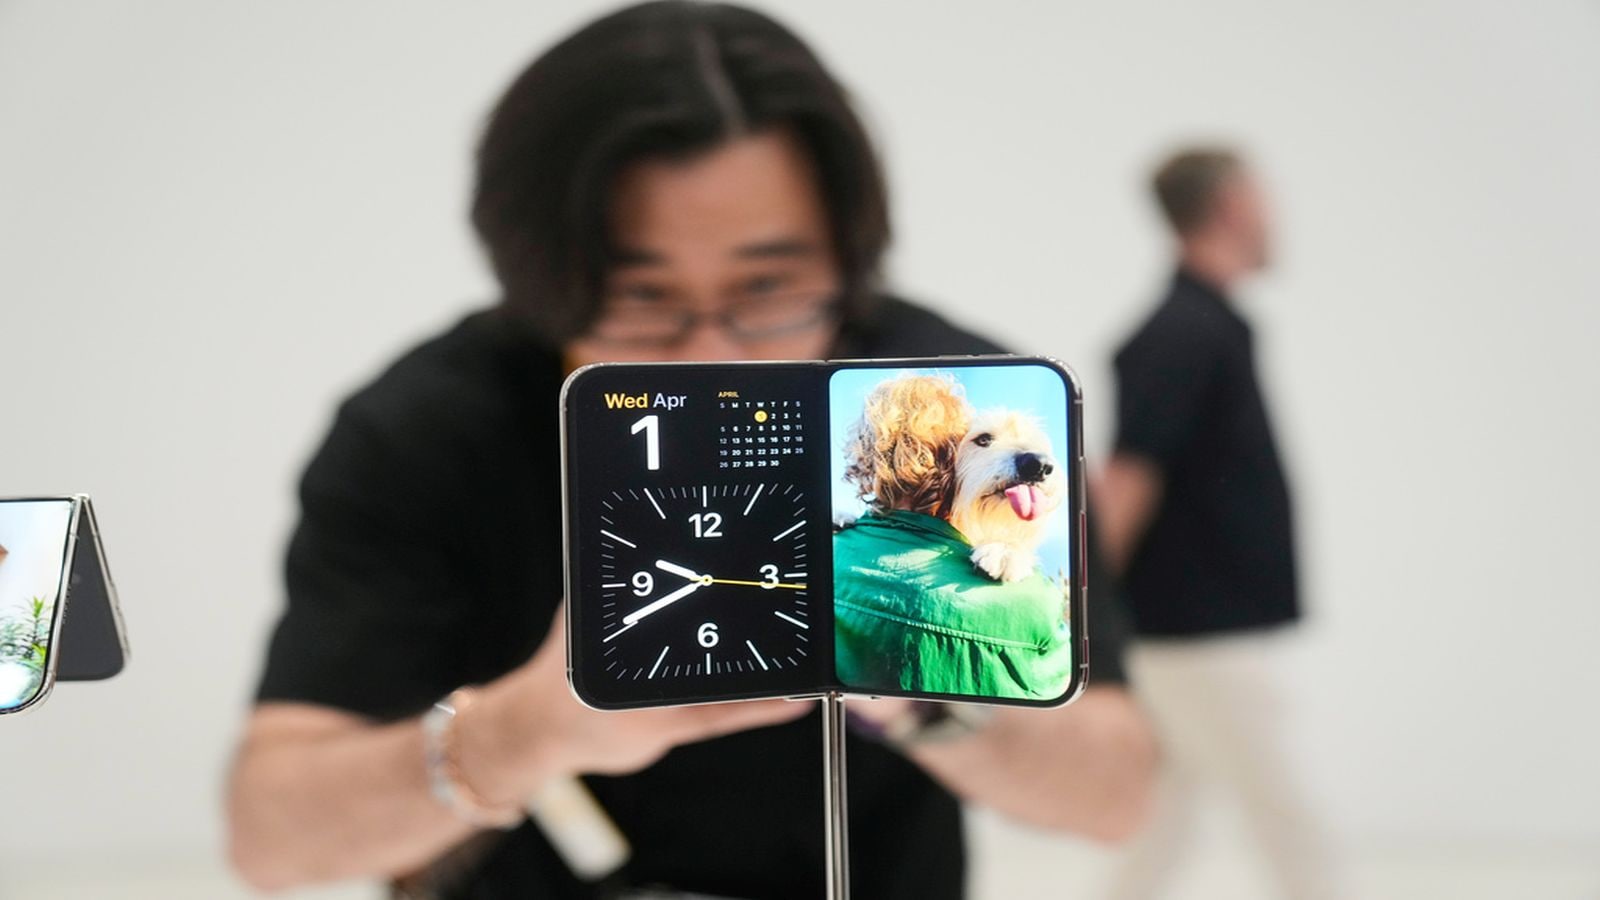
Headline news about a hardware launch selling out in three minutes with shipping dates slipping into the following year rarely measures true demand. In October 2026, preorders for the Apple iPhone Duo opened at prices starting at $1,999 and reaching $3,199 for top storage tiers, with shipping windows across colors and capacities quickly stretching into late January 2027. By mid-November 2026, quoted delivery windows for new orders compressed back into mid-to-late December, while some buyers who had seen January estimates received units ahead of schedule.
A superficial report treats an instant sellout and a multi-month backlog as proof of runaway, permanent demand. That interpretation conflates initial launch allocation with sustained market absorption. When an operator or investor reads a "sold out in three minutes" headline, the real analytical question is not whether the first batch cleared, but which operational constraint set the size of that batch and how fast production capacity can close the gap between order intake and fulfillment.
Deconstructing the Competitor Narrative
Typical launch-day coverage follows a predictable sequence: announce a dramatic sellout window, cite the longest quoted shipping estimate, note uniform depletion across colors and storage options, and infer that demand overwhelms supply indefinitely. That logic rests on three weak assumptions.
First, it treats quoted ship dates as a direct readout of total unit volume. A shipping date reflects the queue depth relative to current weekly output and channel allocation, not an absolute sales figure. When a new form factor—such as a foldable device transitioning from a 5.4-inch outer display to a 7.6-inch inner display—enters volume production, initial allocation can be tight even when total addressable demand is still being tested.
Second, it treats simultaneous depletion across SKUs as evidence of uniform consumer preference. When every storage tier and finish slips into a later shipping window within a short opening window, the primary signal is often a shared bottleneck—such as display assembly, hinge mechanisms, or dedicated final-assembly lines—rather than identical demand for every configuration.
Third, it assumes static lead times. A headline published on preorder day captures a snapshot at peak initial queue formation. As factory ramp curves stabilize, safety buffers adjust, or early order cancellations and re-allocations occur, quoted delivery windows can move forward rather than stay frozen in the distant future.
The Supply-Demand Mismatch Framework
To analyze a hardware launch rigorously, separate the mechanics into four distinct operational variables rather than lumping everything into "high demand."
- Initial Allocation Pool ($A_0$): The volume of finished and near-finished units committed to the preorder and launch-day window across direct and retail channels. Apple routinely reserves stock for walk-in retail and carrier partners alongside online preorders, meaning online queue depth reflects a subset of total launch supply.
- Arrival Rate ($\lambda$): The rate at which orders arrive per minute or hour during the opening window. High brand awareness and pent-up curiosity around a flagship or first-generation foldable naturally spike $\lambda$ right at launch.
- Replenishment Rate ($\mu$): The net rate at which usable inventory enters the fulfillment pool over time, governed by component yields, assembly line throughput, logistics transit, and channel allocation rules.
- Backlog Buffer ($B_t$): The cumulative gap between orders placed and units shipped at time $t$. A ship date slipping from October into January indicates that early $\lambda$ exceeded early $\mu$ enough to push new orders past near-term output commitments.
The core cause-and-effect relationship is straightforward. A three-minute sellout happens whenever $\lambda \times \Delta t \ge A_0$ over a three-minute interval. If $A_0$ is modest because a new hardware architecture faces tight early yields or deliberate staging, even moderate-to-strong demand clears the opening allocation fast. Conversely, if $\mu$ ramps faster than initial pessimism assumes—as reflected when November shipping estimates pull back into December—the backlog compresses without requiring a collapse in underlying interest.
Why First-Generation Hardware Behaves Differently
Launching a first-generation foldable or major structural redesign alters the cost and yield curve compared to an incremental spec refresh. A dual-screen or folding form factor introduces mechanical tolerances, specialized display layers, and structural assemblies that do not share identical maturity profiles with mature slab designs.
In early production of complex hardware, yield learning is a primary governor of $\mu$. Even when demand is strong, manufacturers must balance speed against defect rates and reliability standards. Pushing line speed ahead of process stability risks higher rework or warranty exposure later, so disciplined operators stage volume growth as yields stabilize.
Price elasticity also operates differently at the top of the market. At $1,999 to $3,199, early buyers skew toward enthusiasts, early adopters, and enterprise or commercial evaluators who prioritize novelty and capability over price sensitivity. That cohort concentrates heavily at the start of the cycle, creating a sharp front-loaded spike in $\lambda$ that may not repeat at the same slope once initial novelty fades.
Consider how two buyers experience the same launch window differently:
- The Day-One Buyer: Places an order within minutes, secures an early wave or launch-window slot, and evaluates the product against immediate expectations and early reviews.
- The Post-Spike Buyer: Shops weeks later, encounters a multi-week or multi-month shipping estimate, and faces a decision choice—wait for the backordered unit, buy an existing alternative immediately, or delay purchase until inventory normalizes.
That second group is where "sold out until January" creates real commercial friction. Every week of delayed delivery exposes fence-sitters to competing devices, holiday gifting deadlines, or changing personal budgets. When delivery estimates shift from January into December, some of that lost holiday urgency can be recovered.
Cause-and-Effect Chains Launch Coverage Misses
Surface reporting usually stops at "demand is high, wait times are long." A deeper operational reading traces four second-order effects that determine whether a hot launch becomes a durable product line.
Channel Tension Between Online Queue and Retail Shelves
When online shipping dates slip deep into a future window while walk-in store stock is scarce or sold out, customer frustration rises in visible places. Yet holding back too much inventory for walk-in stores lengthens online queues, while dumping everything into online preorders leaves retail floors empty. Operators constantly trade off queue visibility online against tactile conversion in physical stores, especially for a new form factor where handling the hinge and screen transition matters to undecided buyers.
Inventory Allocation Across Regions and Configurations
Even when a device sells out broadly, regional logistics and country-specific allocations create uneven wait times. Reports from late November 2026 showed U.S. online delivery estimates moving into mid-to-late December alongside similar mid-December windows in markets such as Japan. Differences in how fast lead times improve across regions signal how regional supply pools and transit schedules are rebalanced as output scales.
Serviceability and Lifecycle Readiness
A complex physical device does not end at checkout. Expanding self-repair parts and tools—such as offering parts and tools for the iPhone Duo alongside other recent hardware—changes long-term ownership economics. Service parts compete for precision components during tight supply periods, yet making parts available signals confidence in long-term maintainability and supports secondary-market value once initial shortages ease.
Cadence Pressure on Subsequent Generations
A fast sellout on Generation 1 creates momentum, yet it also compresses learning cycles when a successor is already in development. If a second-generation model is targeted for roughly a year later, engineering and supply teams must simultaneously scale current fulfillment, digest early field feedback, and lock in tooling and components for the next release. Demand on Version 1 validates the category, while execution on Version 2 tests whether the architecture can scale cost-effectively and reliably.
Distinguishing Verified Facts From Analytical Hypotheses
Disciplined decision-making requires separating what is established from what is inferred.
Known Facts (as of late November 2026):
- Apple unveiled the iPhone Duo in September 2026, opened preorders on October 16, 2026, and began general availability on October 23, 2026, with pricing starting at $1,999 and reaching $3,199 across storage capacities up to 2TB.
- Opening preorder allocations sold out rapidly, pushing quoted shipping estimates for many configurations into late January 2027.
- By mid-to-late November 2026, quoted delivery windows for new orders improved into mid-to-late December 2026, with at least one buyer who had been quoted January receiving a unit on November 16, 2026.
- Apple began offering parts and tools for self-repair on the iPhone Duo.
Educated Hypotheses (requiring ongoing verification):
- The rapid initial sellout reflects a combination of concentrated early-adopter demand for a new foldable form factor and a staged initial production allocation rather than unlimited multi-quarter demand at $1,999-plus price points.
- The improvement in shipping estimates from January back into December indicates that replenishment ($\mu$) or allocation pacing is progressing faster than worst-case launch-day queues implied, though final full-year unit volume depends on sustained post-holiday demand.
- Early buyers who received units ahead of January estimates likely benefited from rolling production batches, channel reallocations, or order cancellations moving people up the queue.
Tactical Playbook for Evaluating and Managing Launch Scarcity
Whether you are an operator managing a product rollout, a retail buyer planning inventory, or an analyst tracking hardware cycles, treat a rapid launch sellout as a diagnostic signal, not a verdict.
- Track Lead-Time Velocity, Not Just Peak Wait Times: Record quoted ship dates at launch, at two weeks, at four weeks, and around major retail peaks. A wait time that shrinks from ten weeks to four weeks tells a very different operational story than a wait time that stays flat or expands.
- Separate Configuration Demand From Line Bottlenecks: Compare availability across storage tiers, colors, and regions. If every option slips together, inspect shared subassemblies and final-line capacity first; if one tier lags alone, re-examine mix forecasting.
- Audit Retail vs. Direct Allocation Trade-Offs: Check whether online delays coincide with empty store shelves. High-touch or unfamiliar hardware often needs floor units to convert mainstream buyers once early enthusiasts have ordered.
- Watch Post-Peak Retention Before Extrapolating: Measure repeat traffic, cancellation rates, and post-holiday order velocity once initial novelty fades. Early spikes rarely prove steady-state run rates on their own.
- Account for Lifecycle and Next-Gen Constraints: Factor service-part allocation and upcoming generational transitions into medium-term supply models. Supply chains rarely optimize a single SKU in isolation.
Limitations of This Analytical Approach
No framework removes uncertainty during a major hardware transition. Exact factory line capacities, confidential component yield curves, and internal channel allocations are proprietary, so external observers must infer capacity from lead times, retail availability, and third-party estimates. Furthermore, consumer behavior around new form factors can shift abruptly based on real-world durability reports, software polish, or competitive pricing moves. Treating lead-time shifts as directional indicators—rather than exact unit counters—prevents overconfidence in either bullish or bearish extremes.
Strategic Play for the Next Cycle
Do not chase three-minute sellout headlines to size inventory or declare category dominance; instead, re-baseline your demand and capacity models 30 to 45 days post-launch using lead-time compression rates and post-holiday order elasticity. If delivery windows pull forward ahead of peak seasonal buying while conversion holds without heavy discounting, scale secondary channels and prepare next-generation tooling with disciplined buffers; if lead times normalize quickly only after the initial enthusiast wave clears, cap long-dated component commitments and focus on margin preservation and reliability across the existing line.